How am I doing?
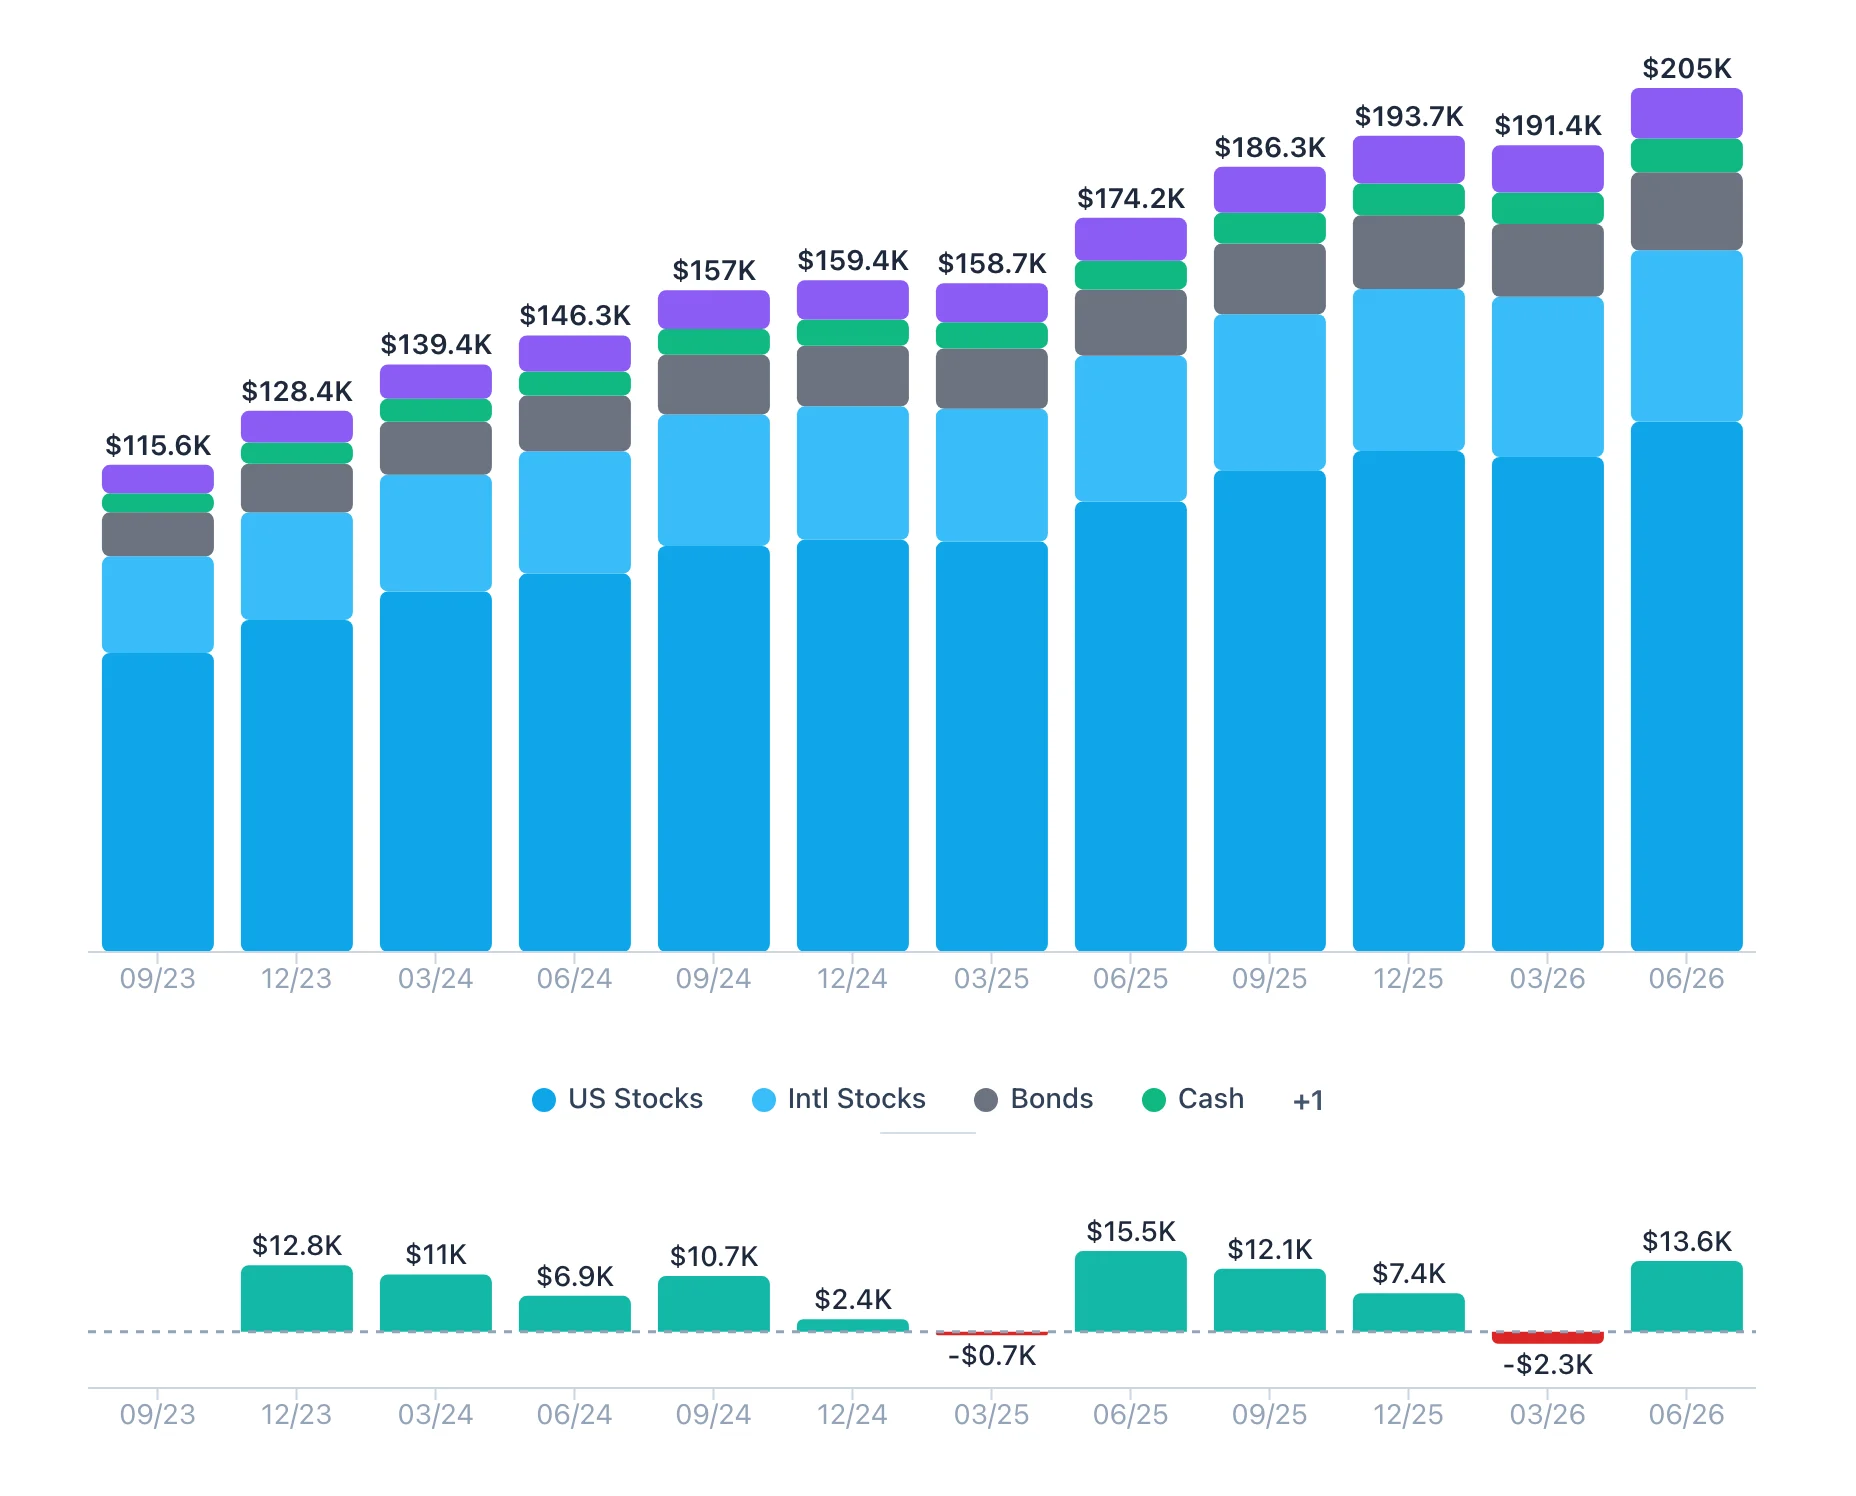
What Your Portfolio Returned
History
Record your balances as often as you like. For each period, invio shows the total change and splits it into what you added and what your investments earned.
Professional-grade tools. Your decisions.
No bank logins · No card required
A sample plan in invio: returns over time, net worth, the order to save in, rebalancing, when you can stop working, a test against market history since 1928, how much you can spend, and withdrawals planned around taxes.
How am I doing?
Record your balances as often as you like. For each period, invio shows the total change and splits it into what you added and what your investments earned.
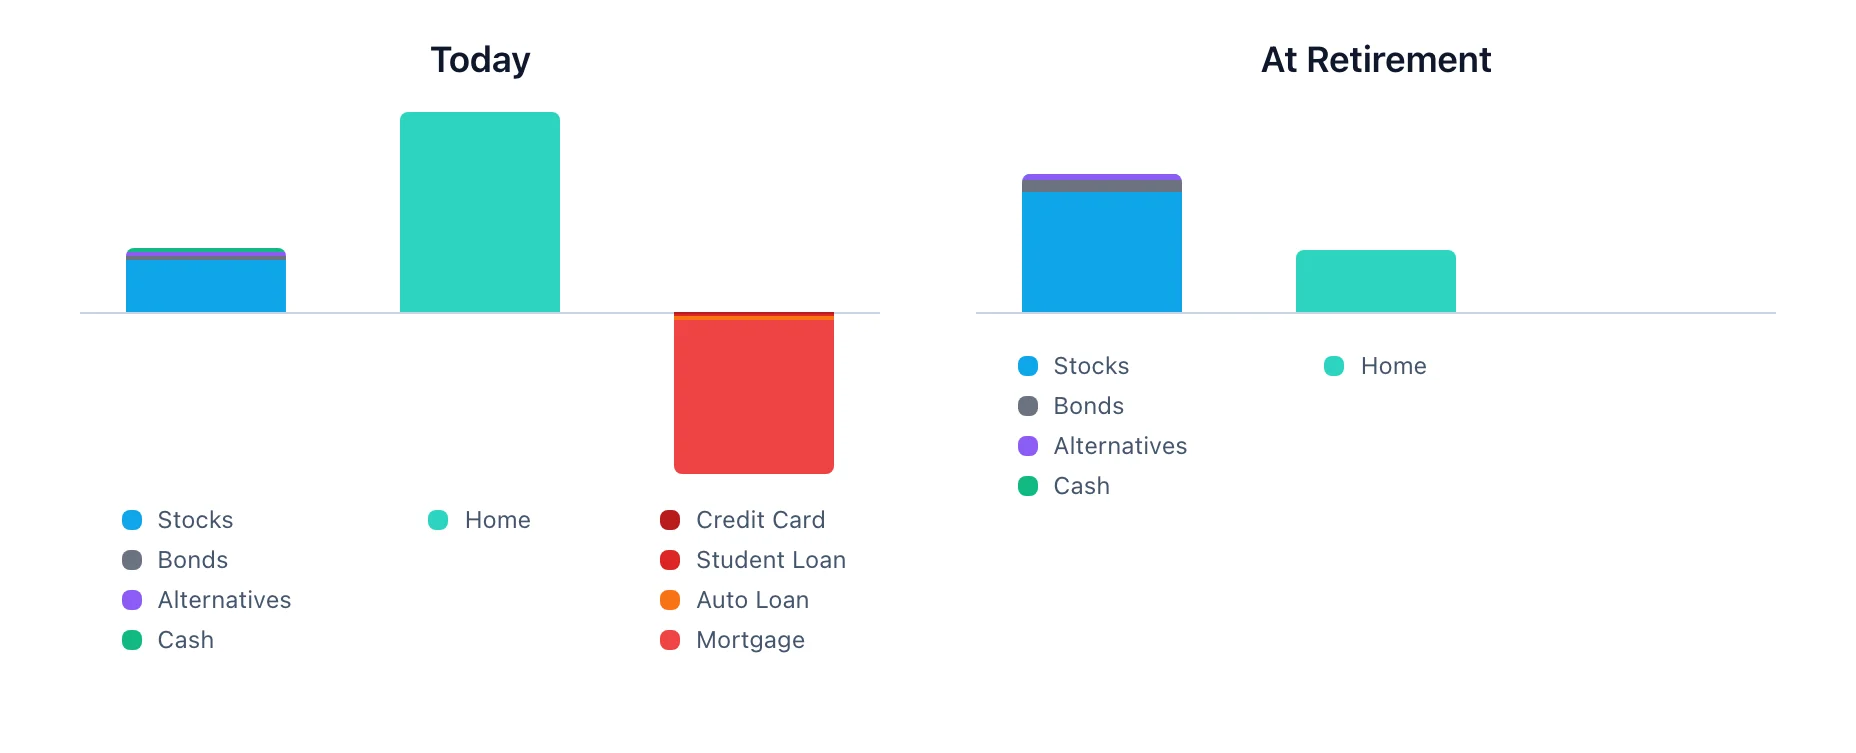
Where do I stand?
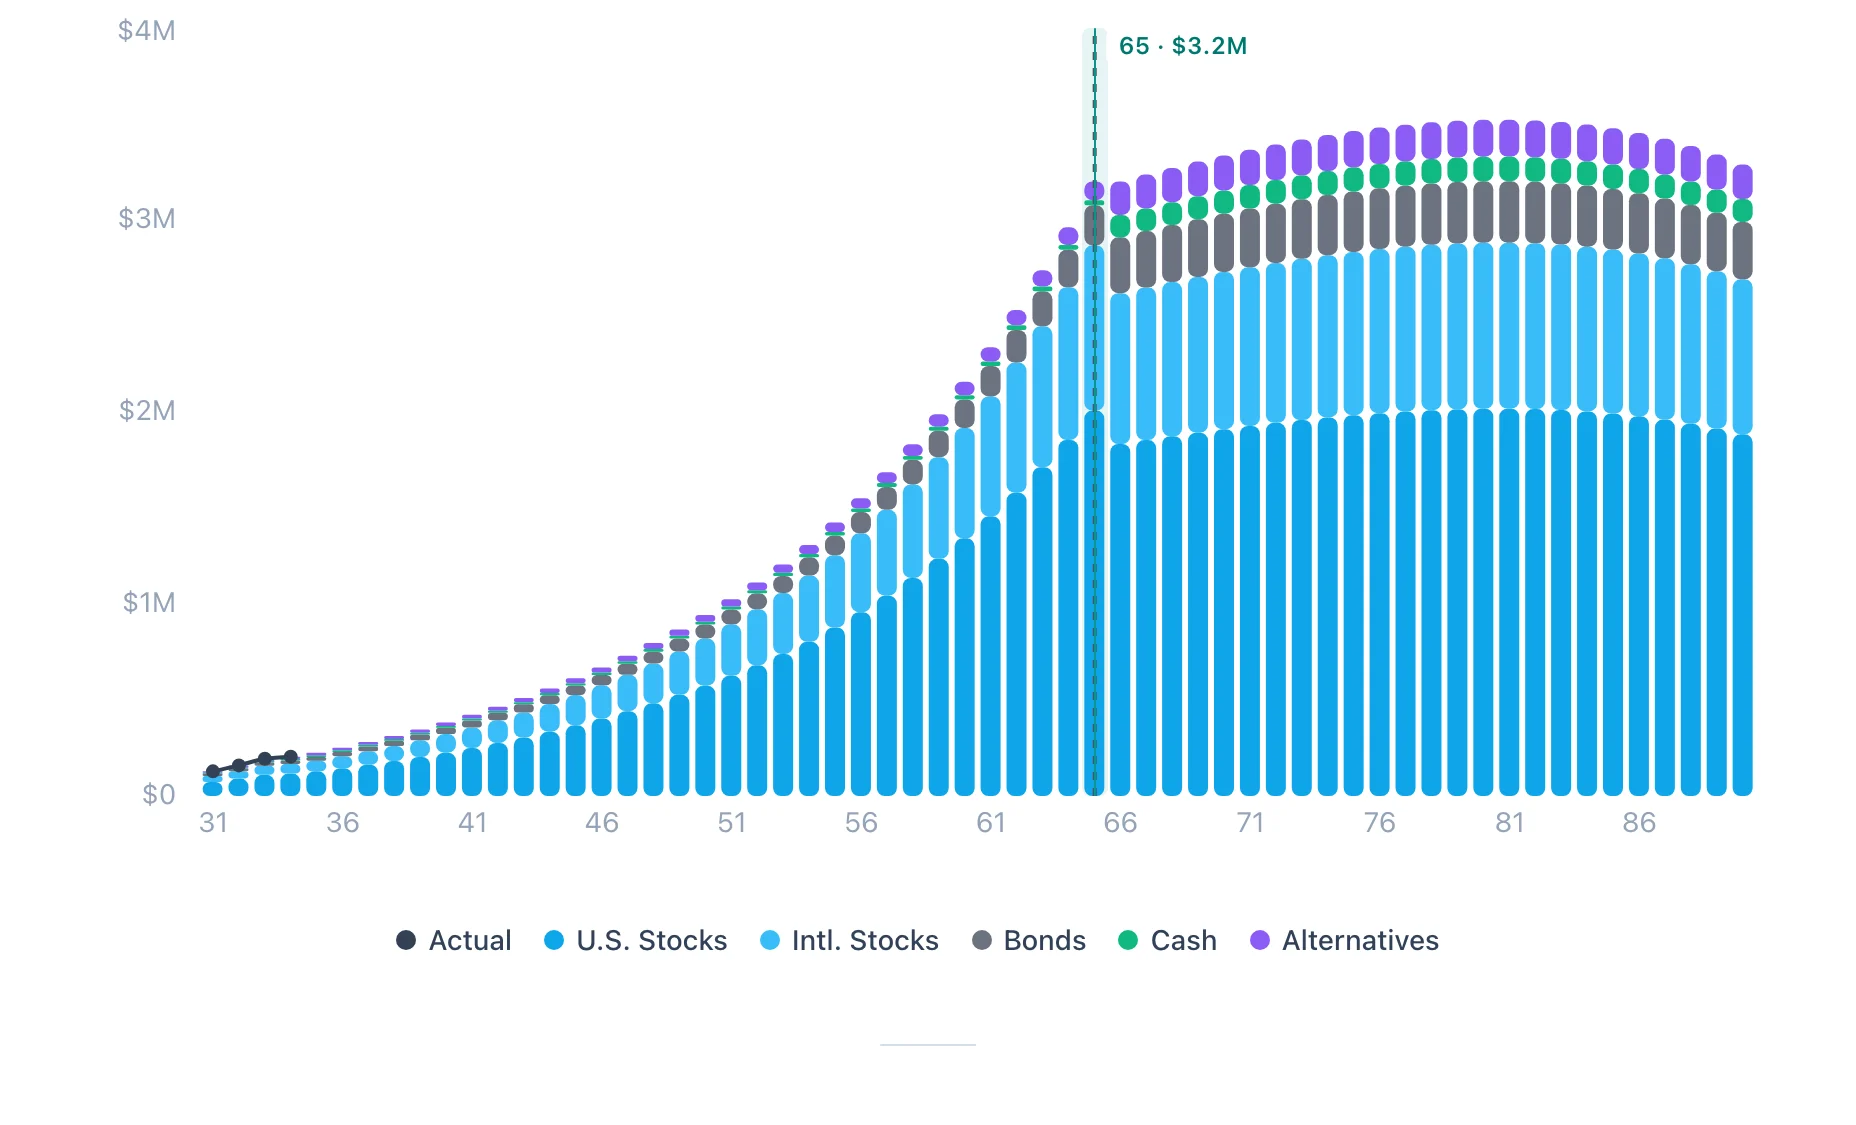
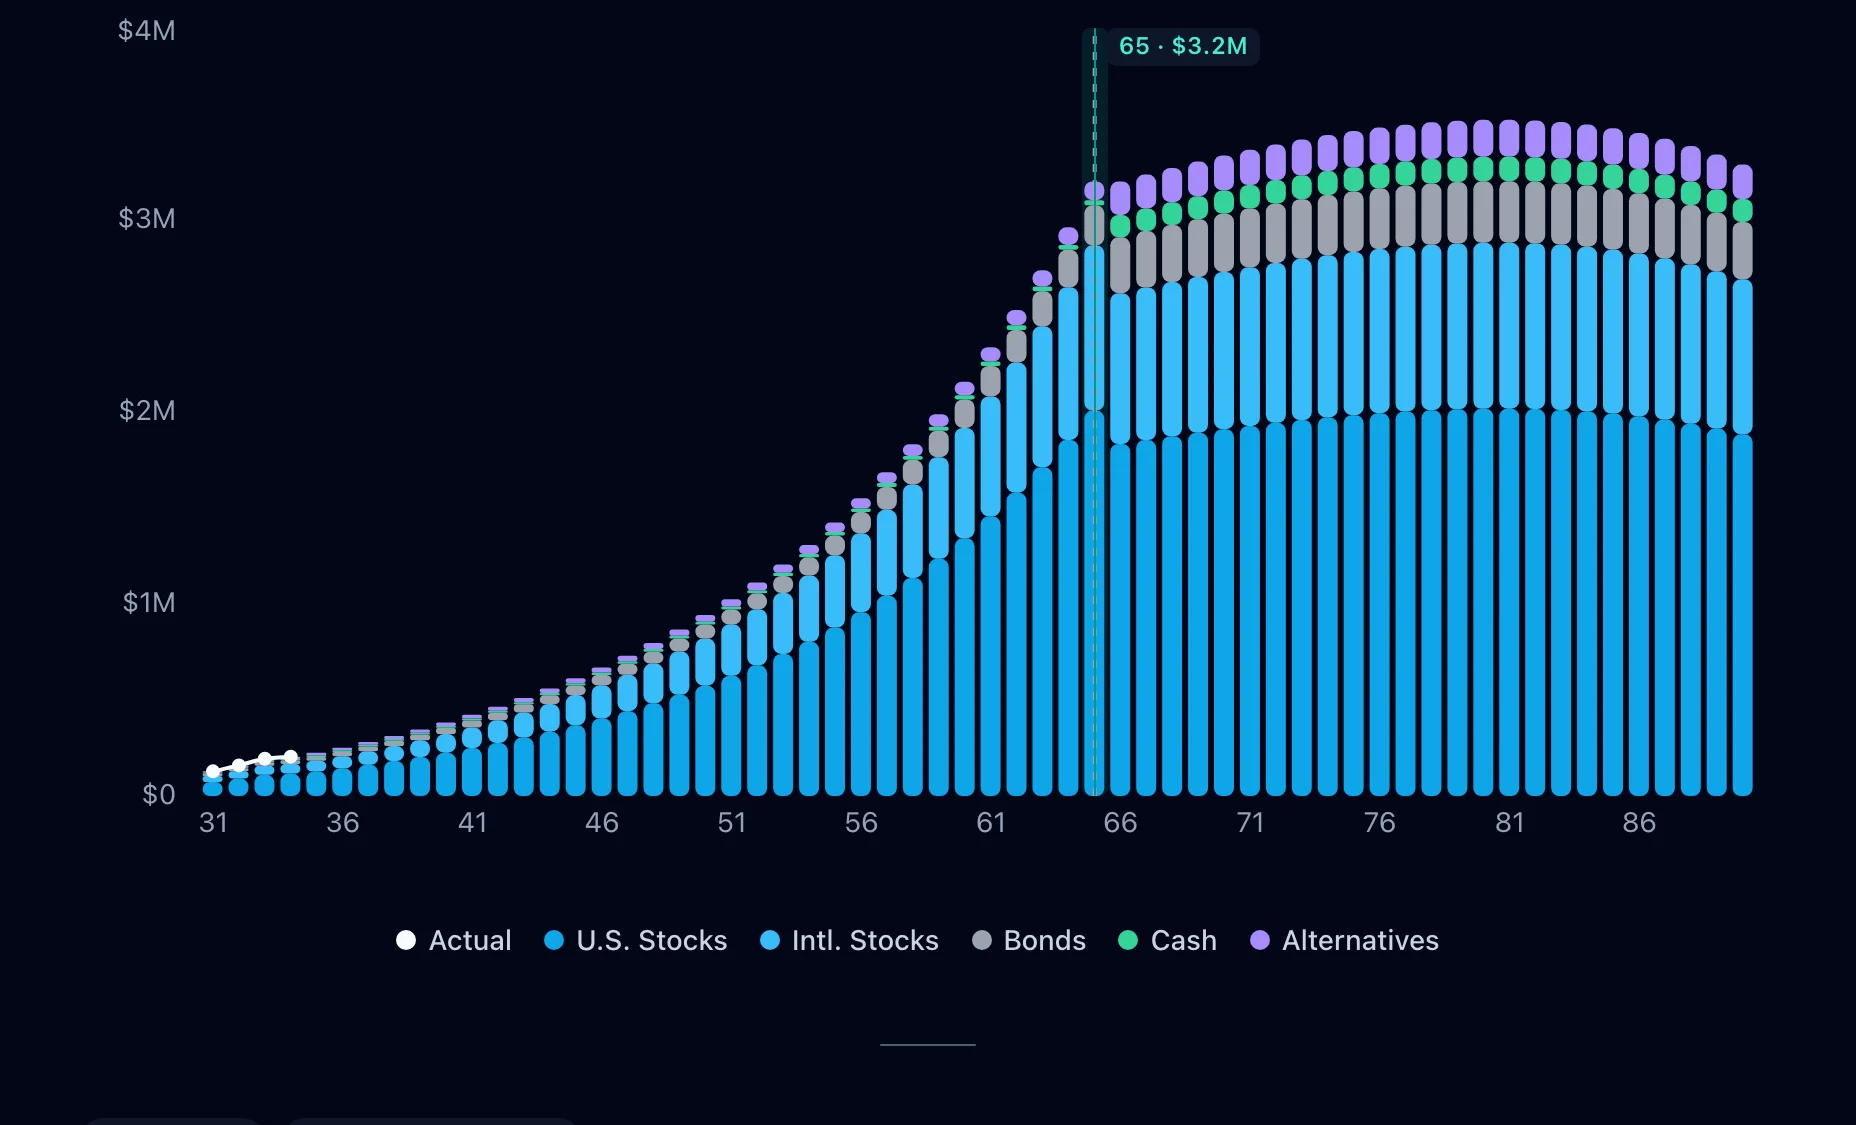
Accounts, home, and debts in one view, projected to the year you retire.
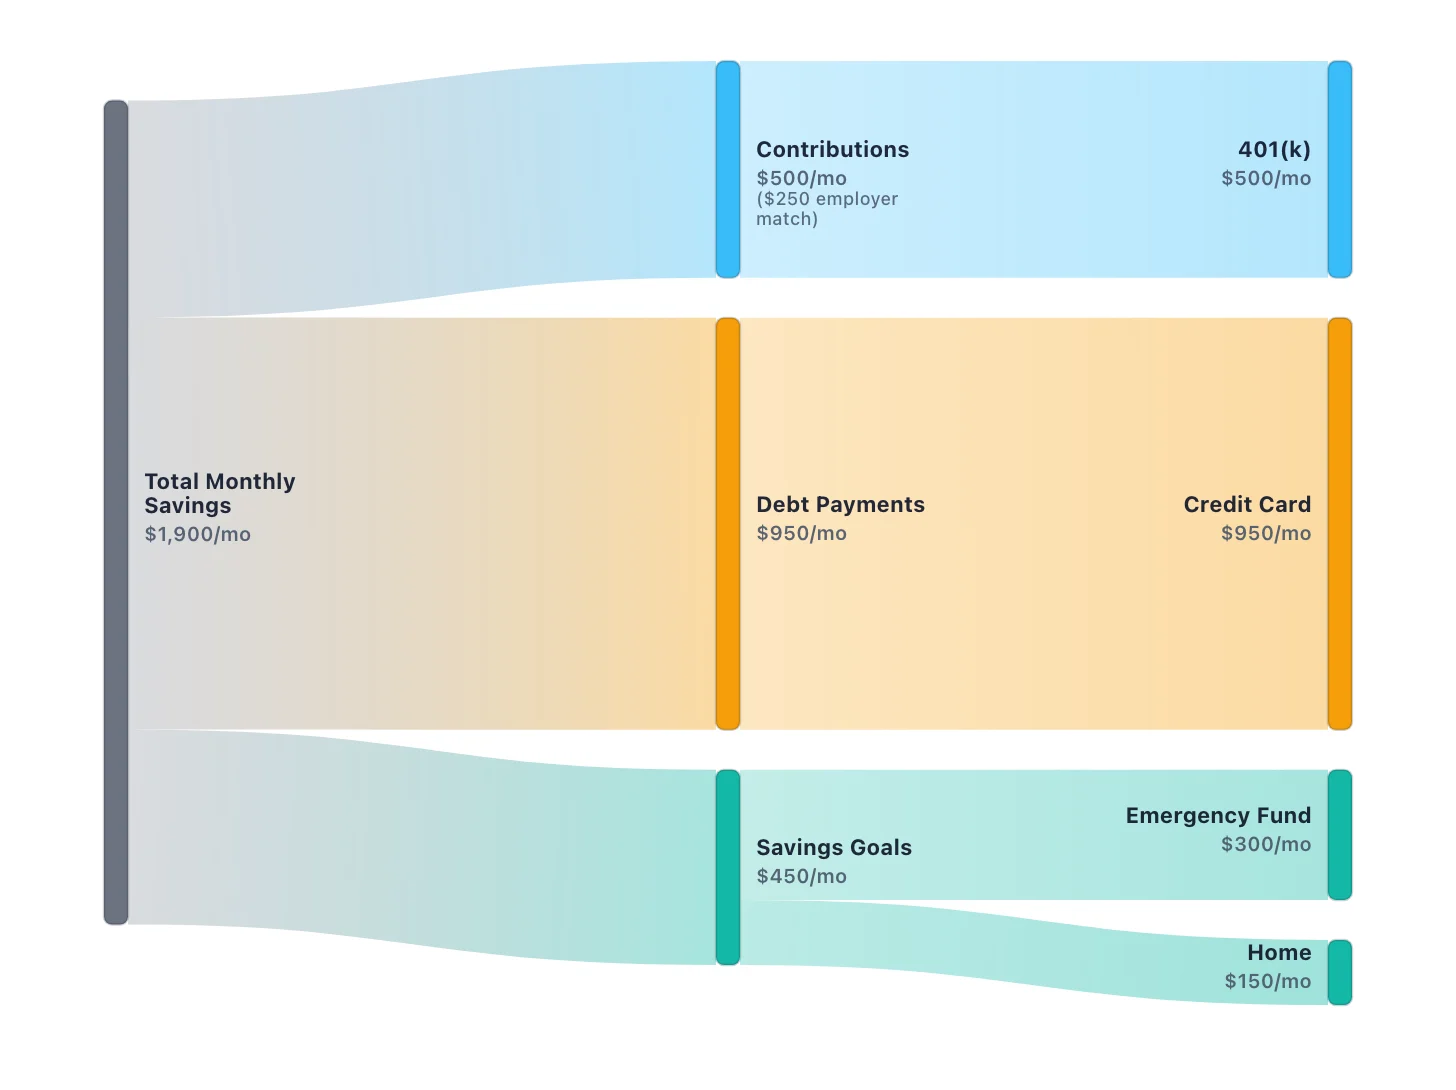
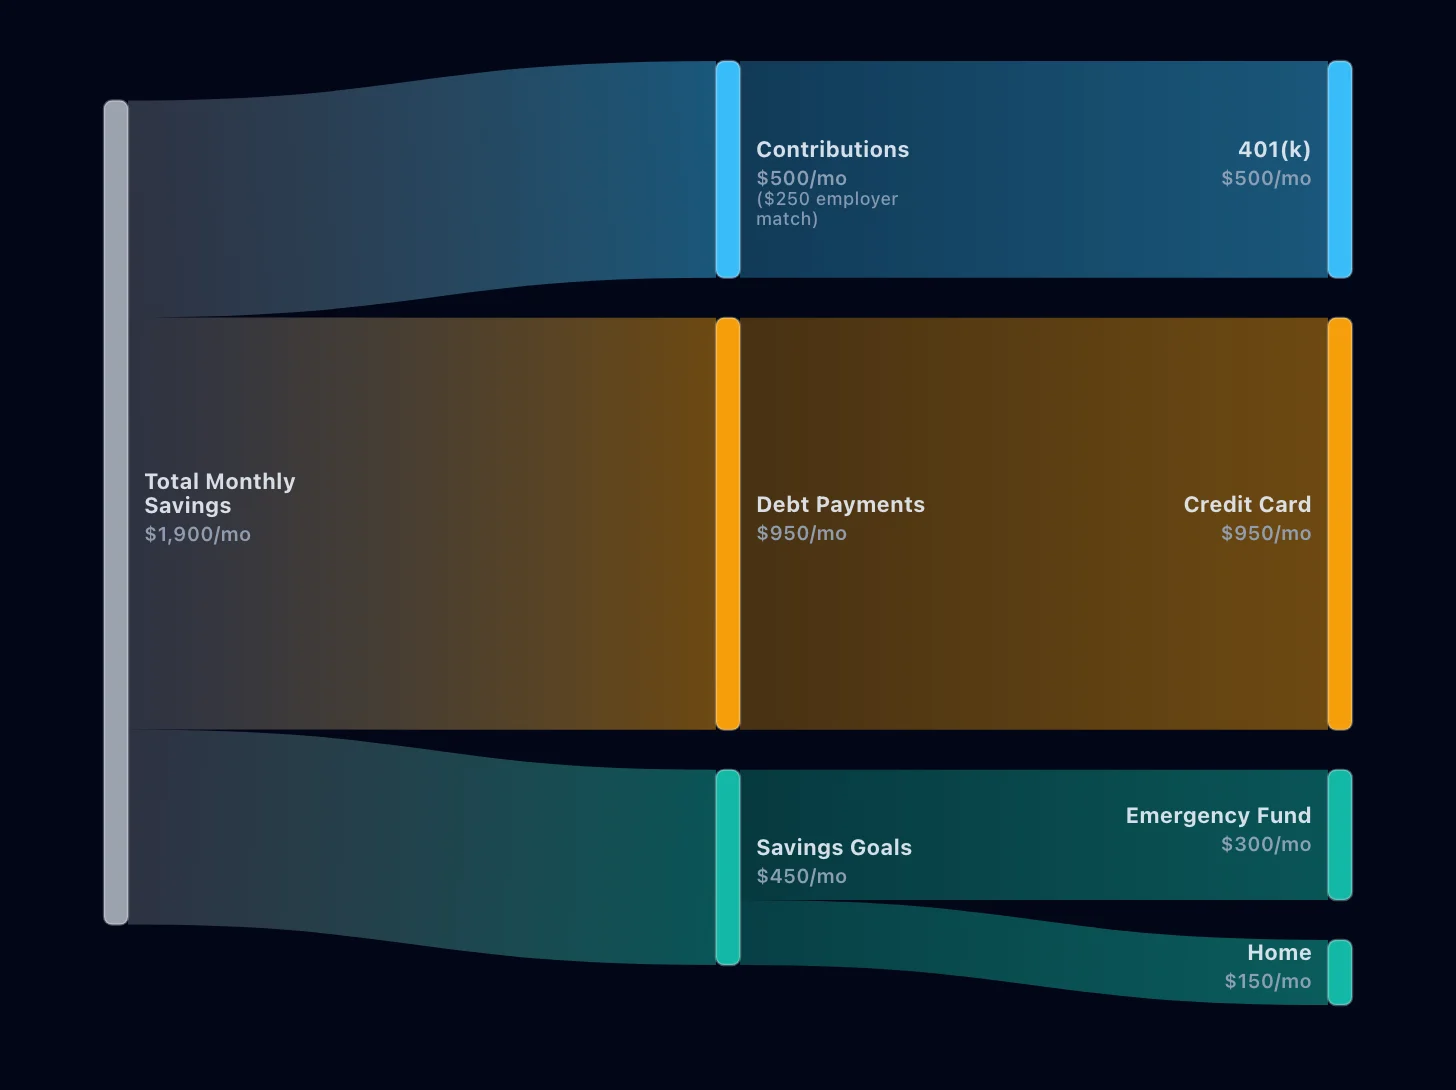
Where should my next dollar go?
By default, invio splits what you save each month: the employer match first, then expensive debt, then tax-advantaged accounts before taxable ones. IRS limits are built in, and Pro lets you set your own order.
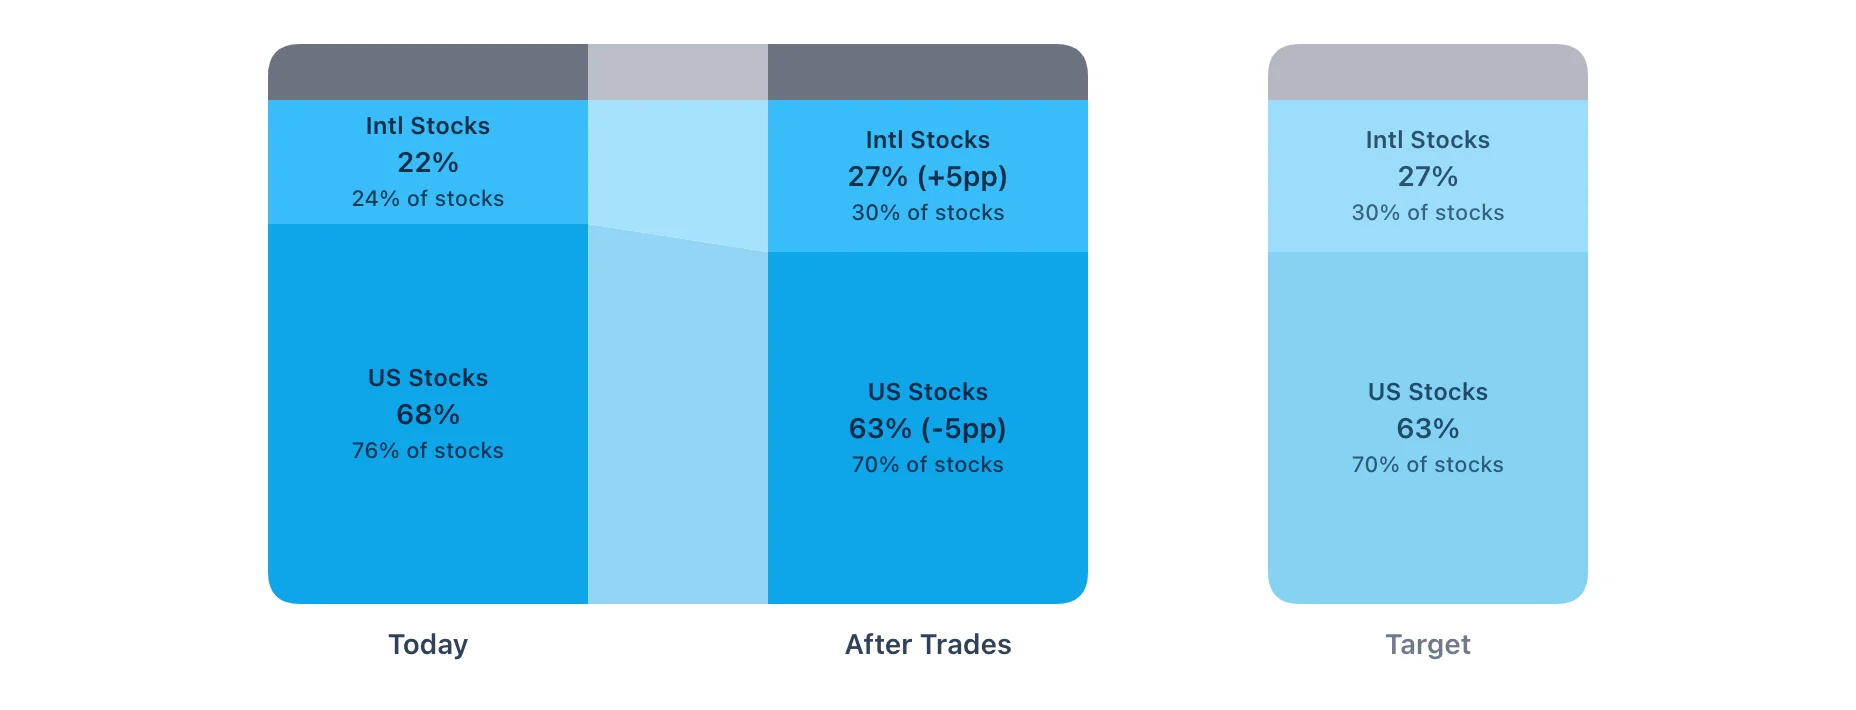
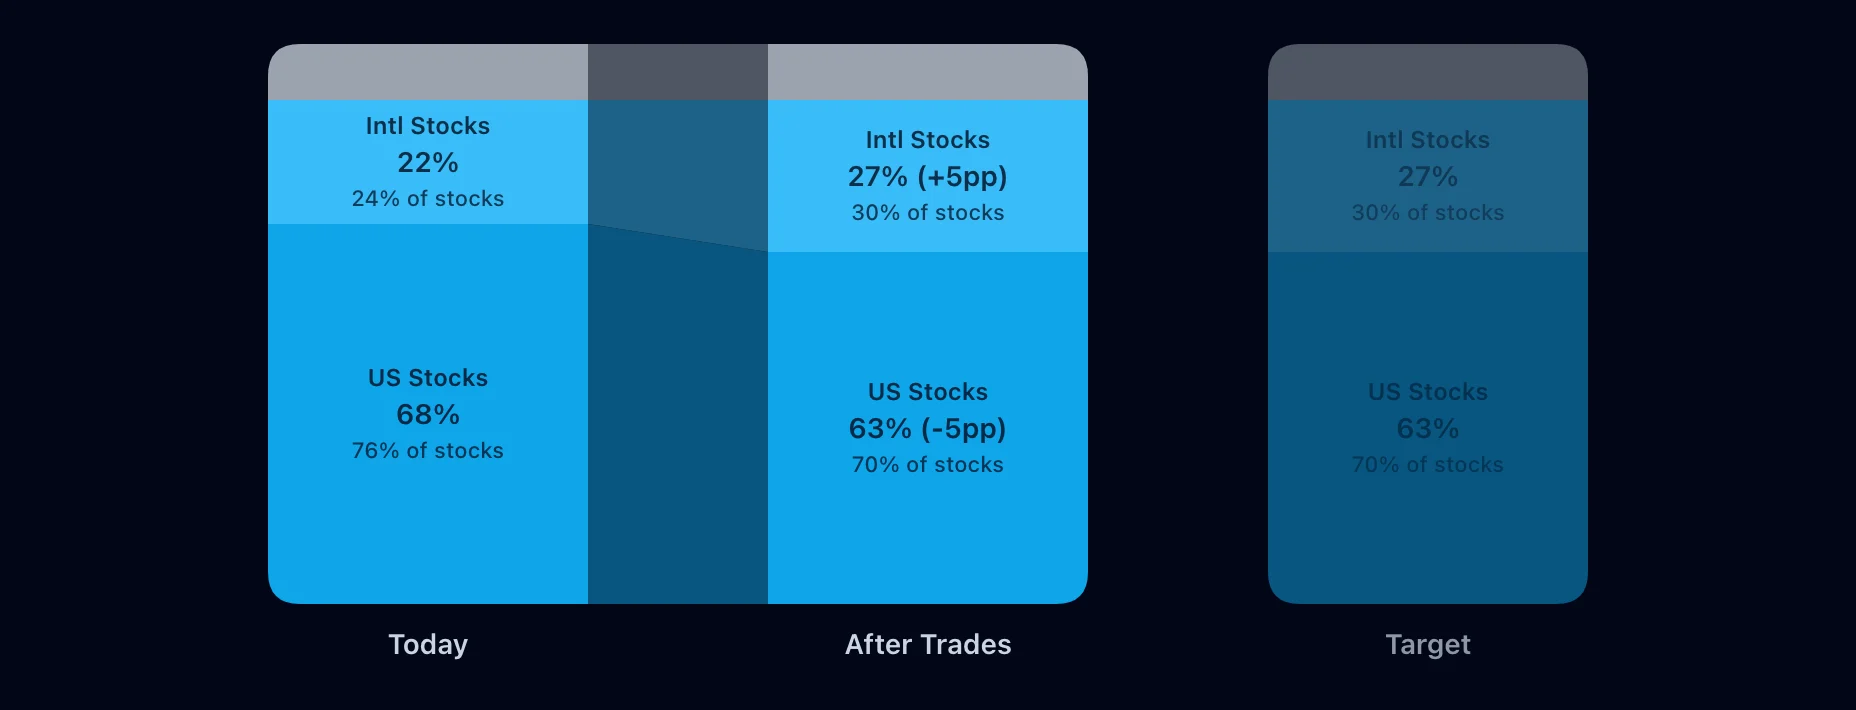
Has my mix drifted?
invio compares your holdings with the target mix you set and lists the trades that close the gap. By default it leaves taxable accounts alone, so rebalancing doesn't trigger capital gains tax.
When can I stop working?
The age you reach financial independence and how long your money lasts after you stop working, in future or today's dollars.
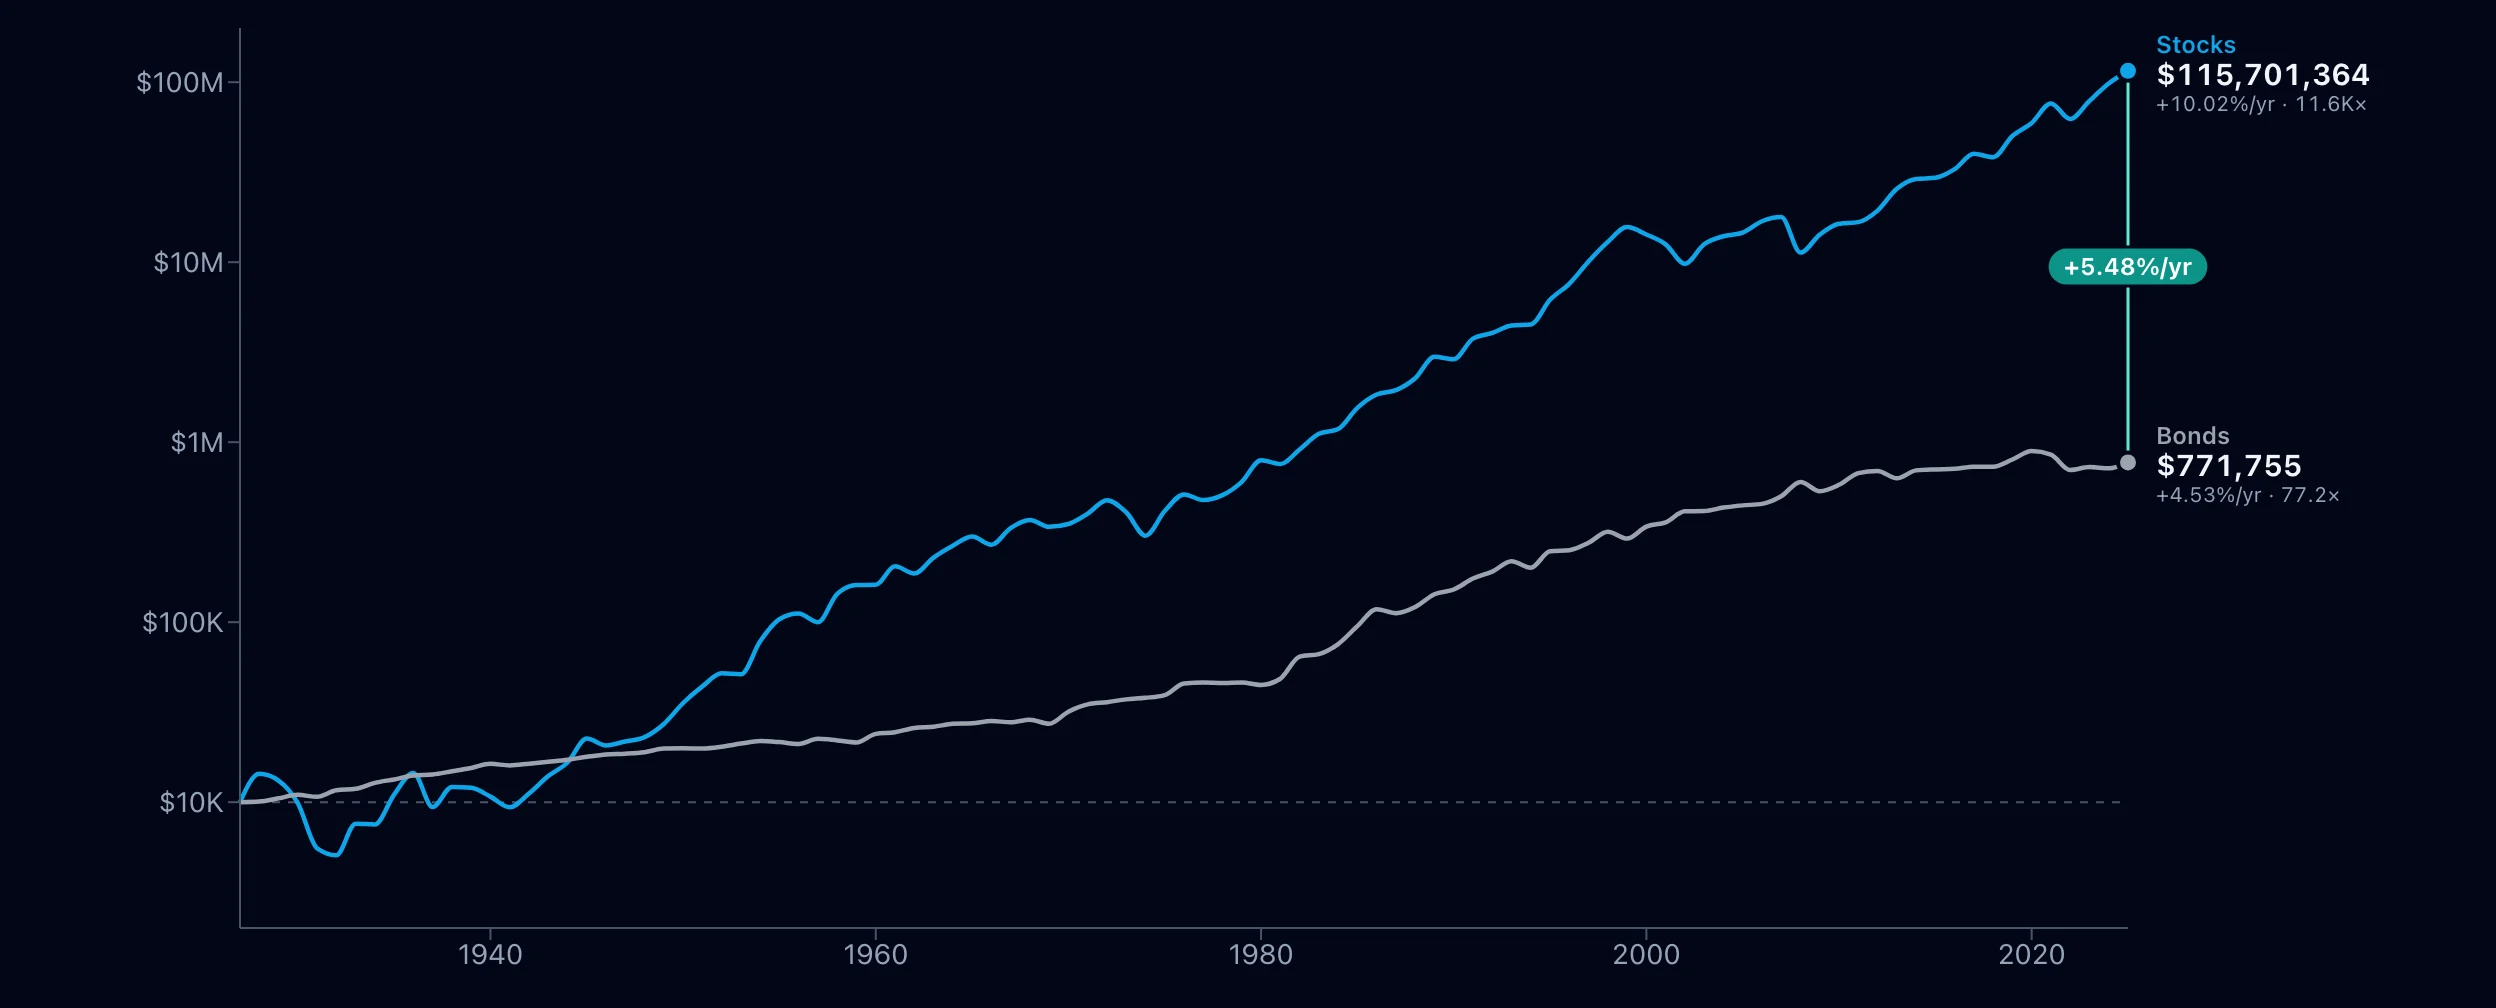
U.S. stock and bond returns since 1871, plus gold, real estate, and more since 1928. See how deep past crashes went and how long they took to recover.
Explore Precedent, free with no account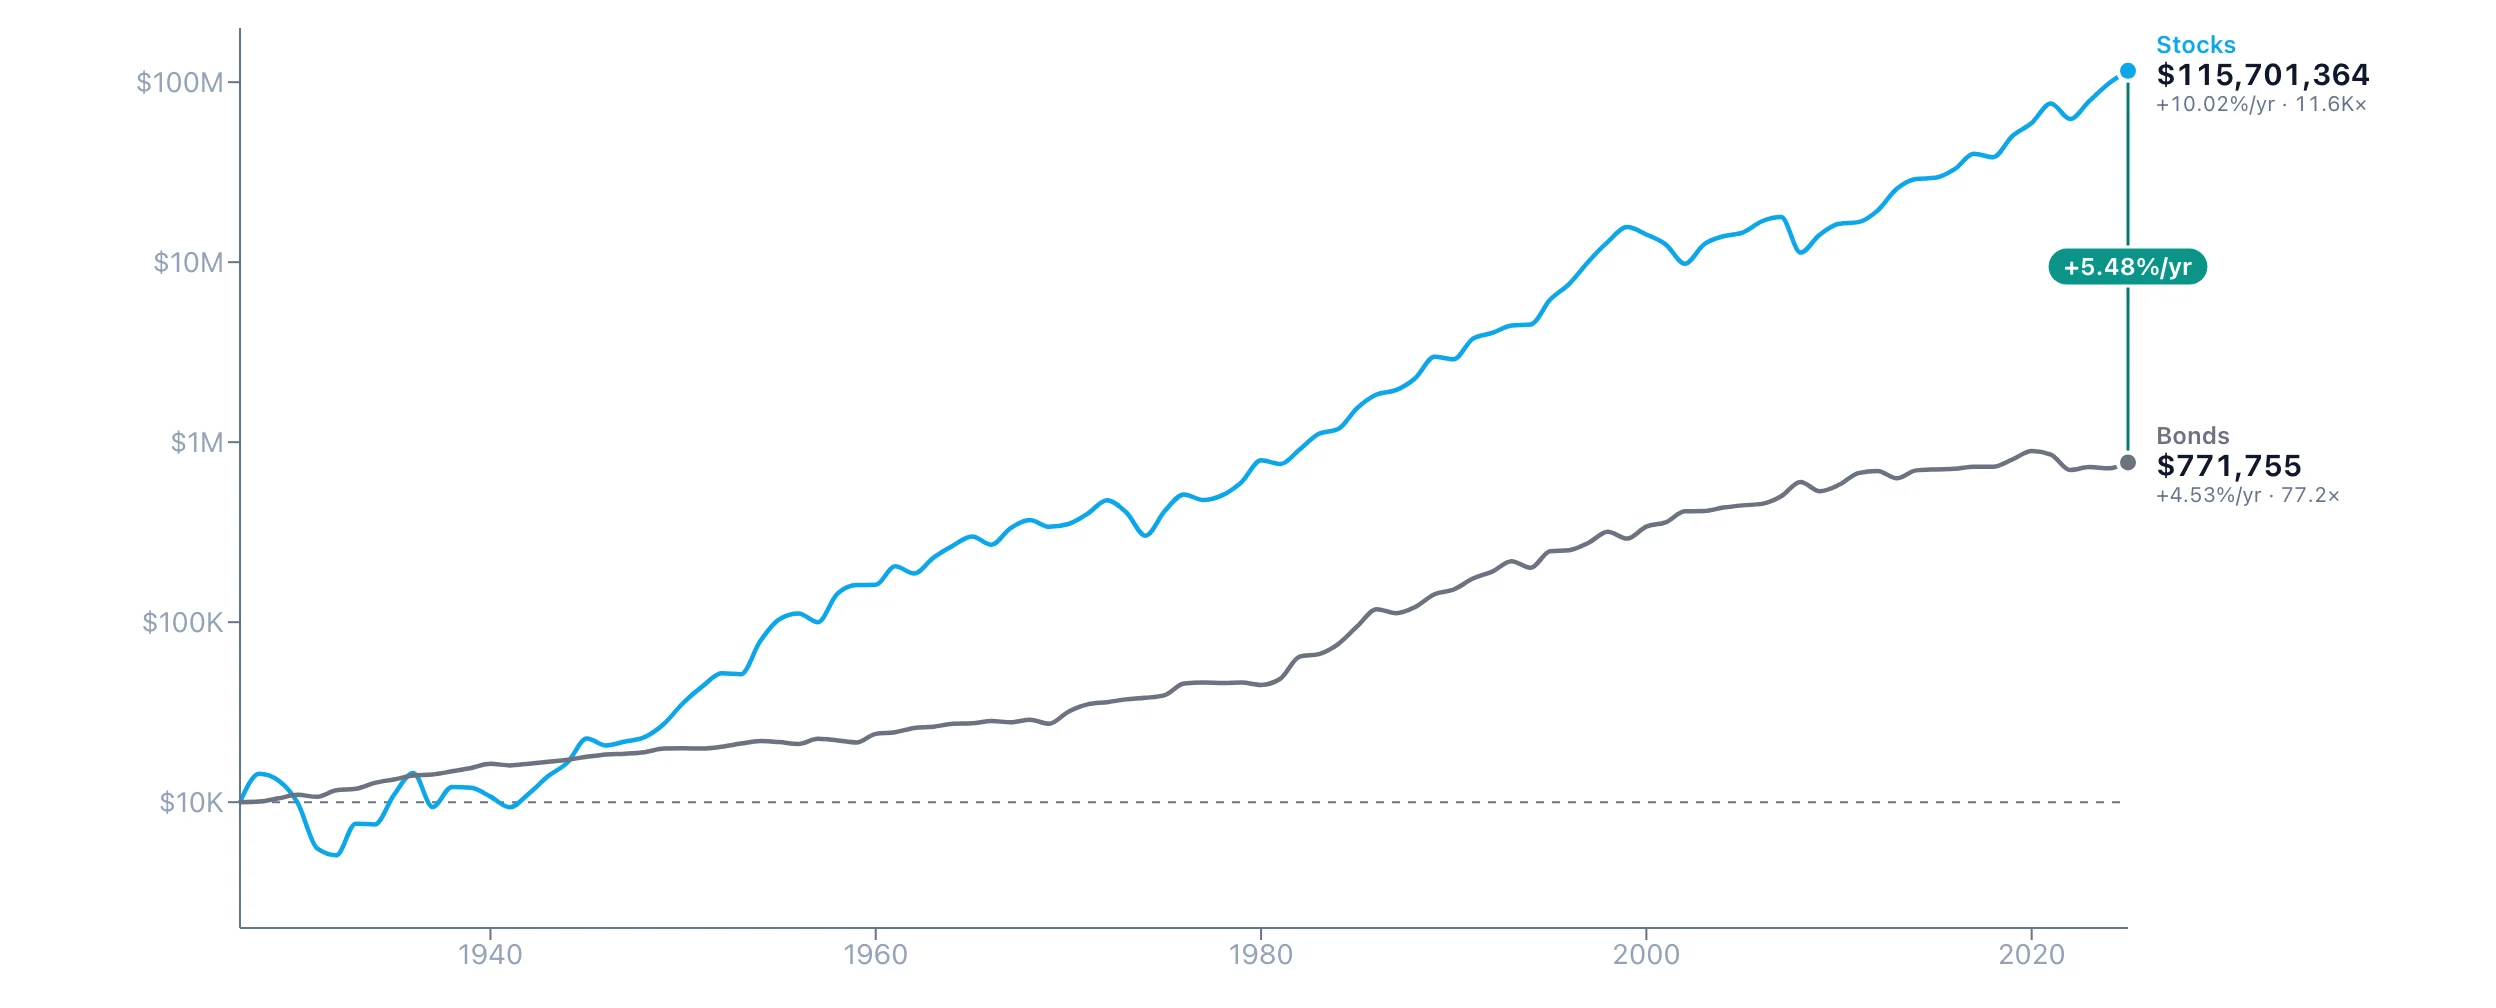
What if markets turn against me?
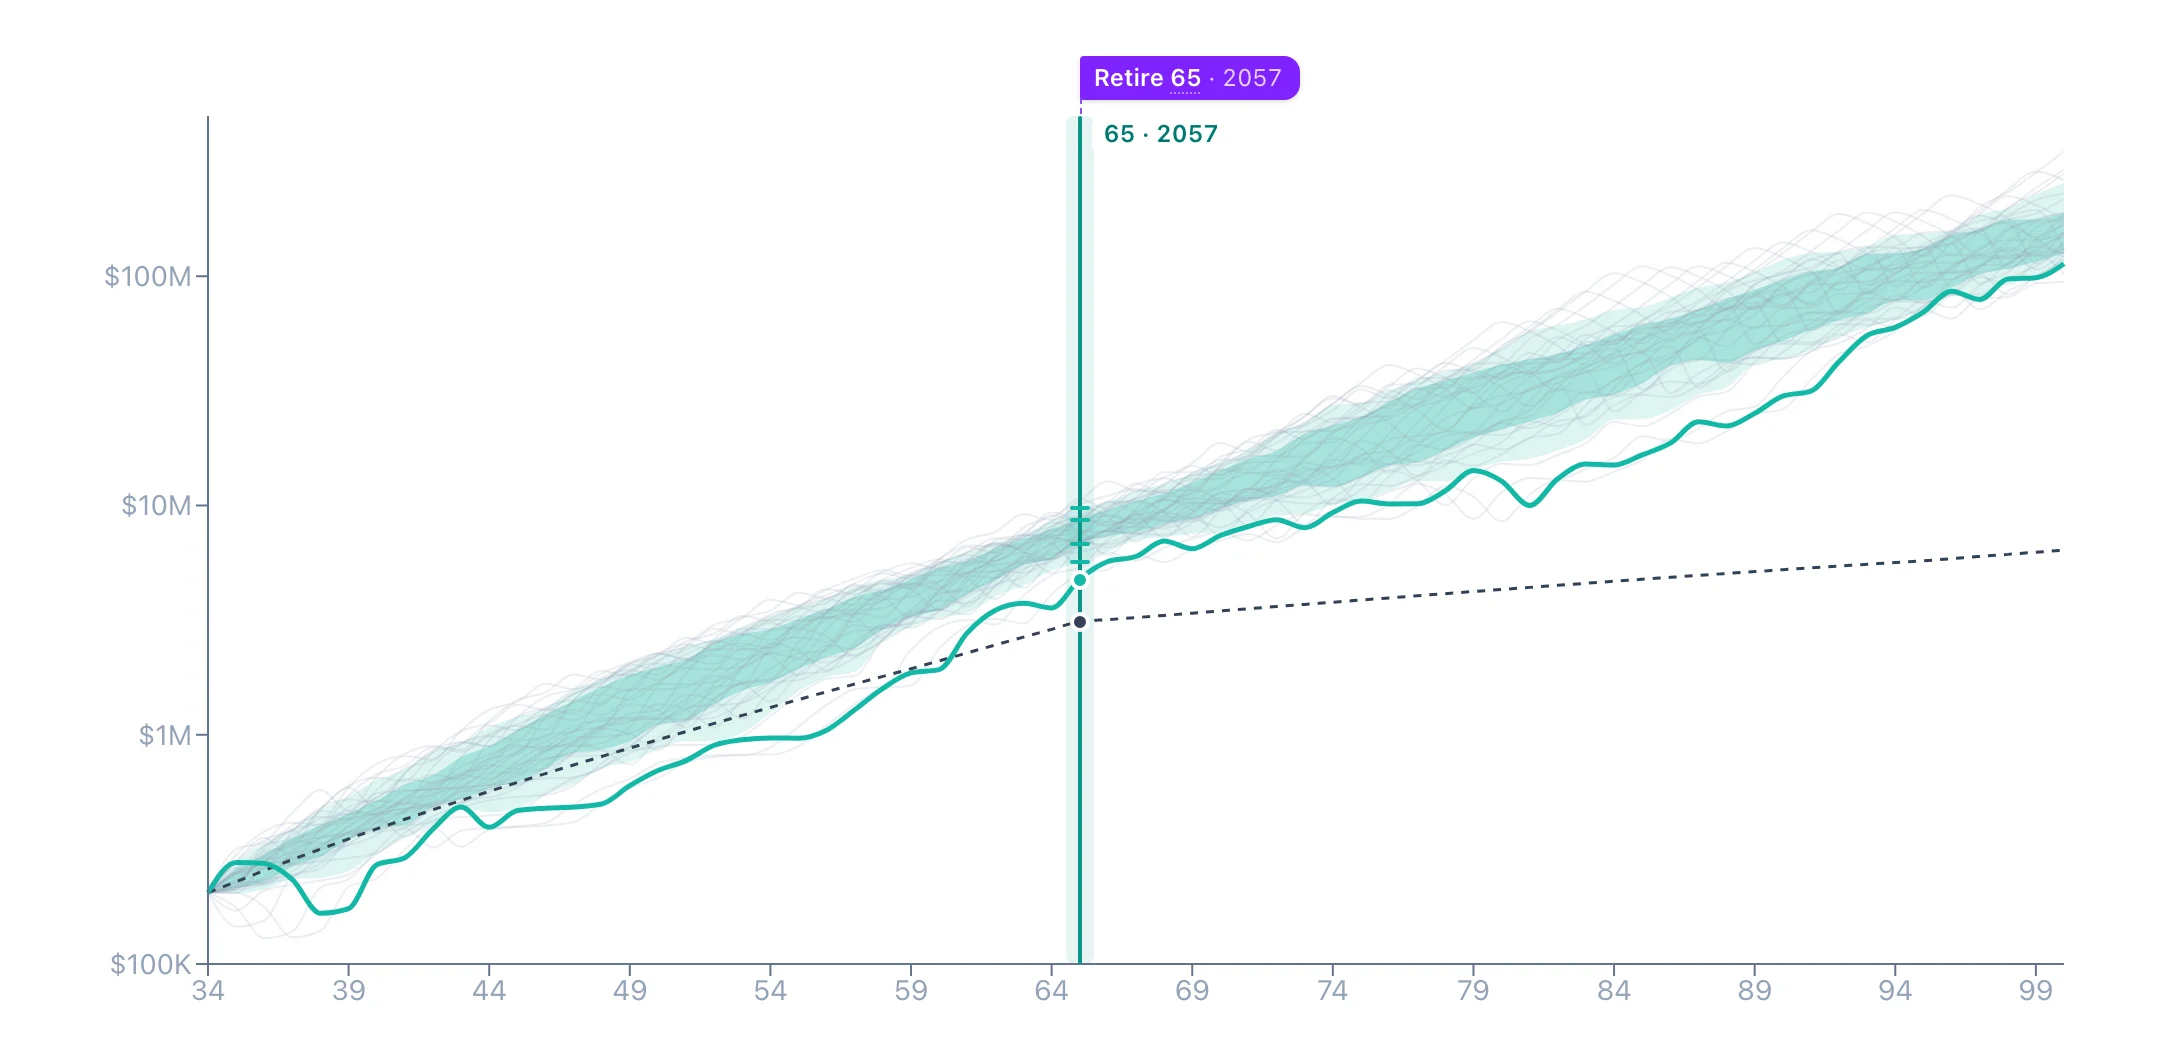
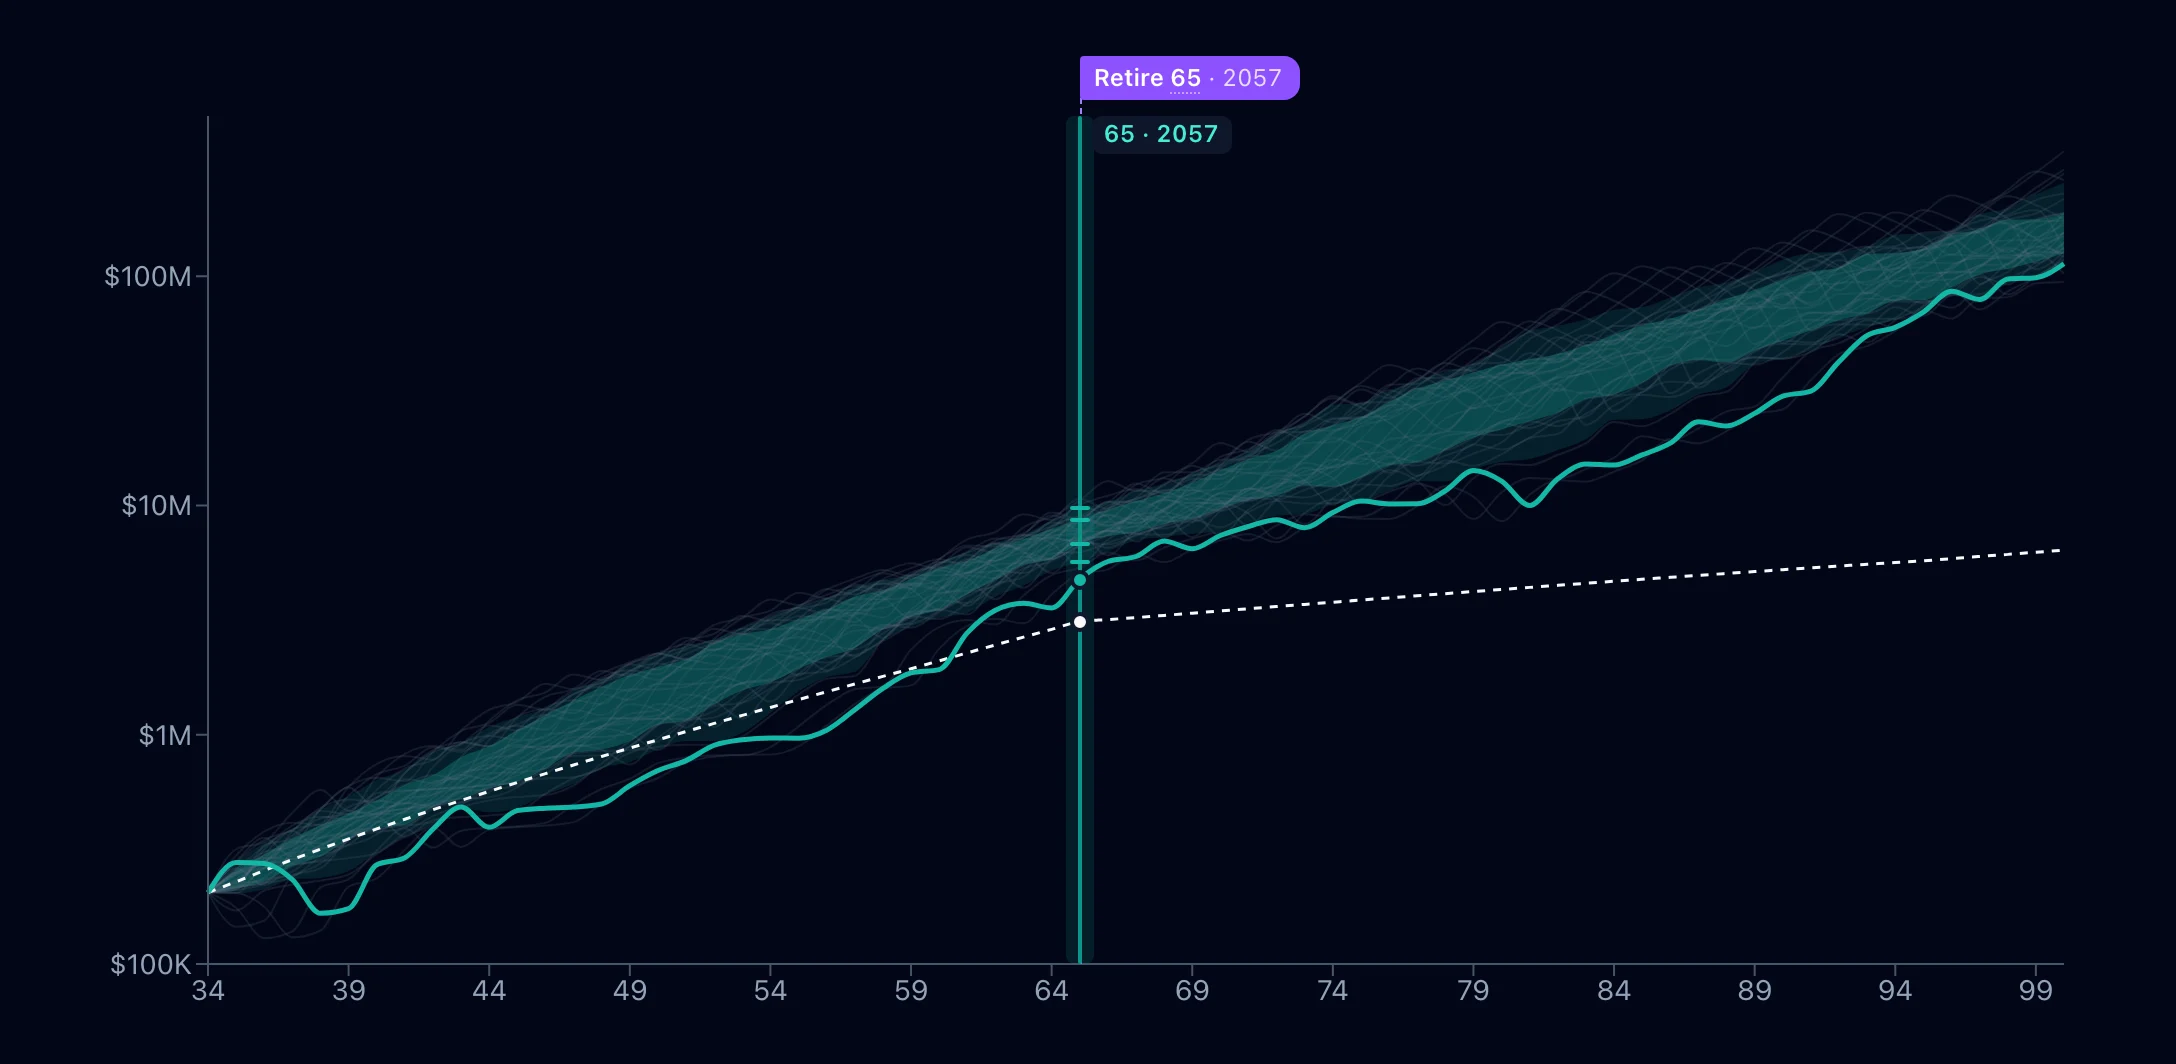
invio runs your plan through historical market returns, one starting year at a time, and draws each path next to your projection.
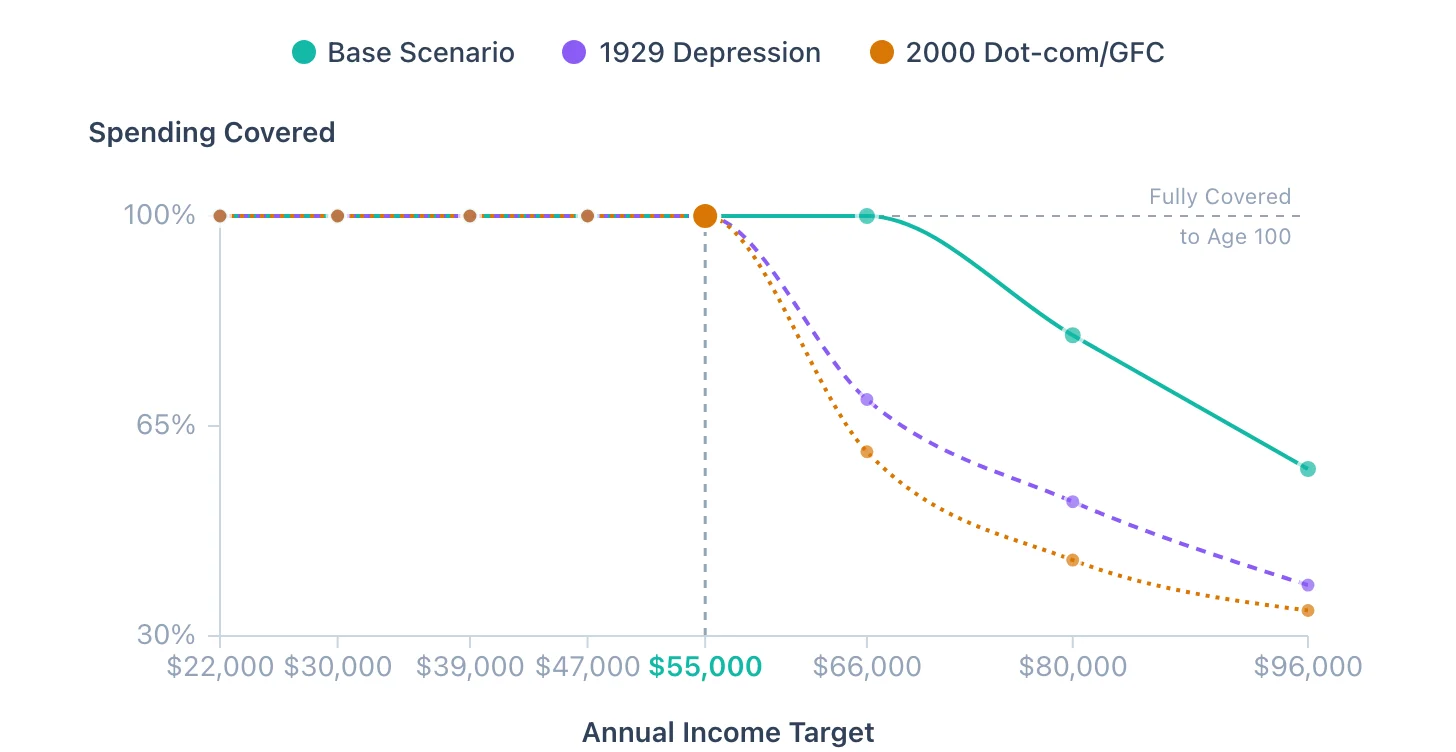
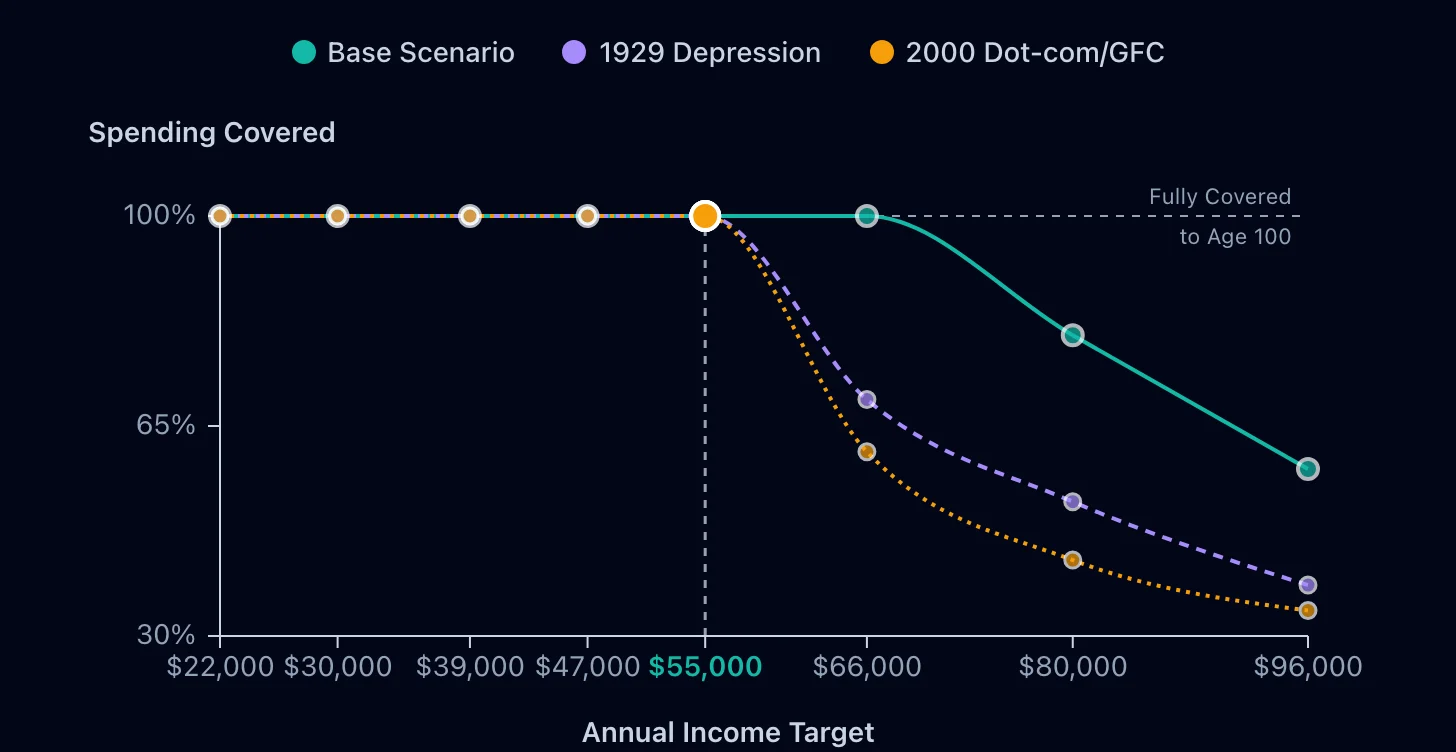
invio tests different yearly spending levels at your assumed returns, then stress-tests each one with retirement starting in 1929 or 2000, just before two major crashes.
How do I turn savings into income?
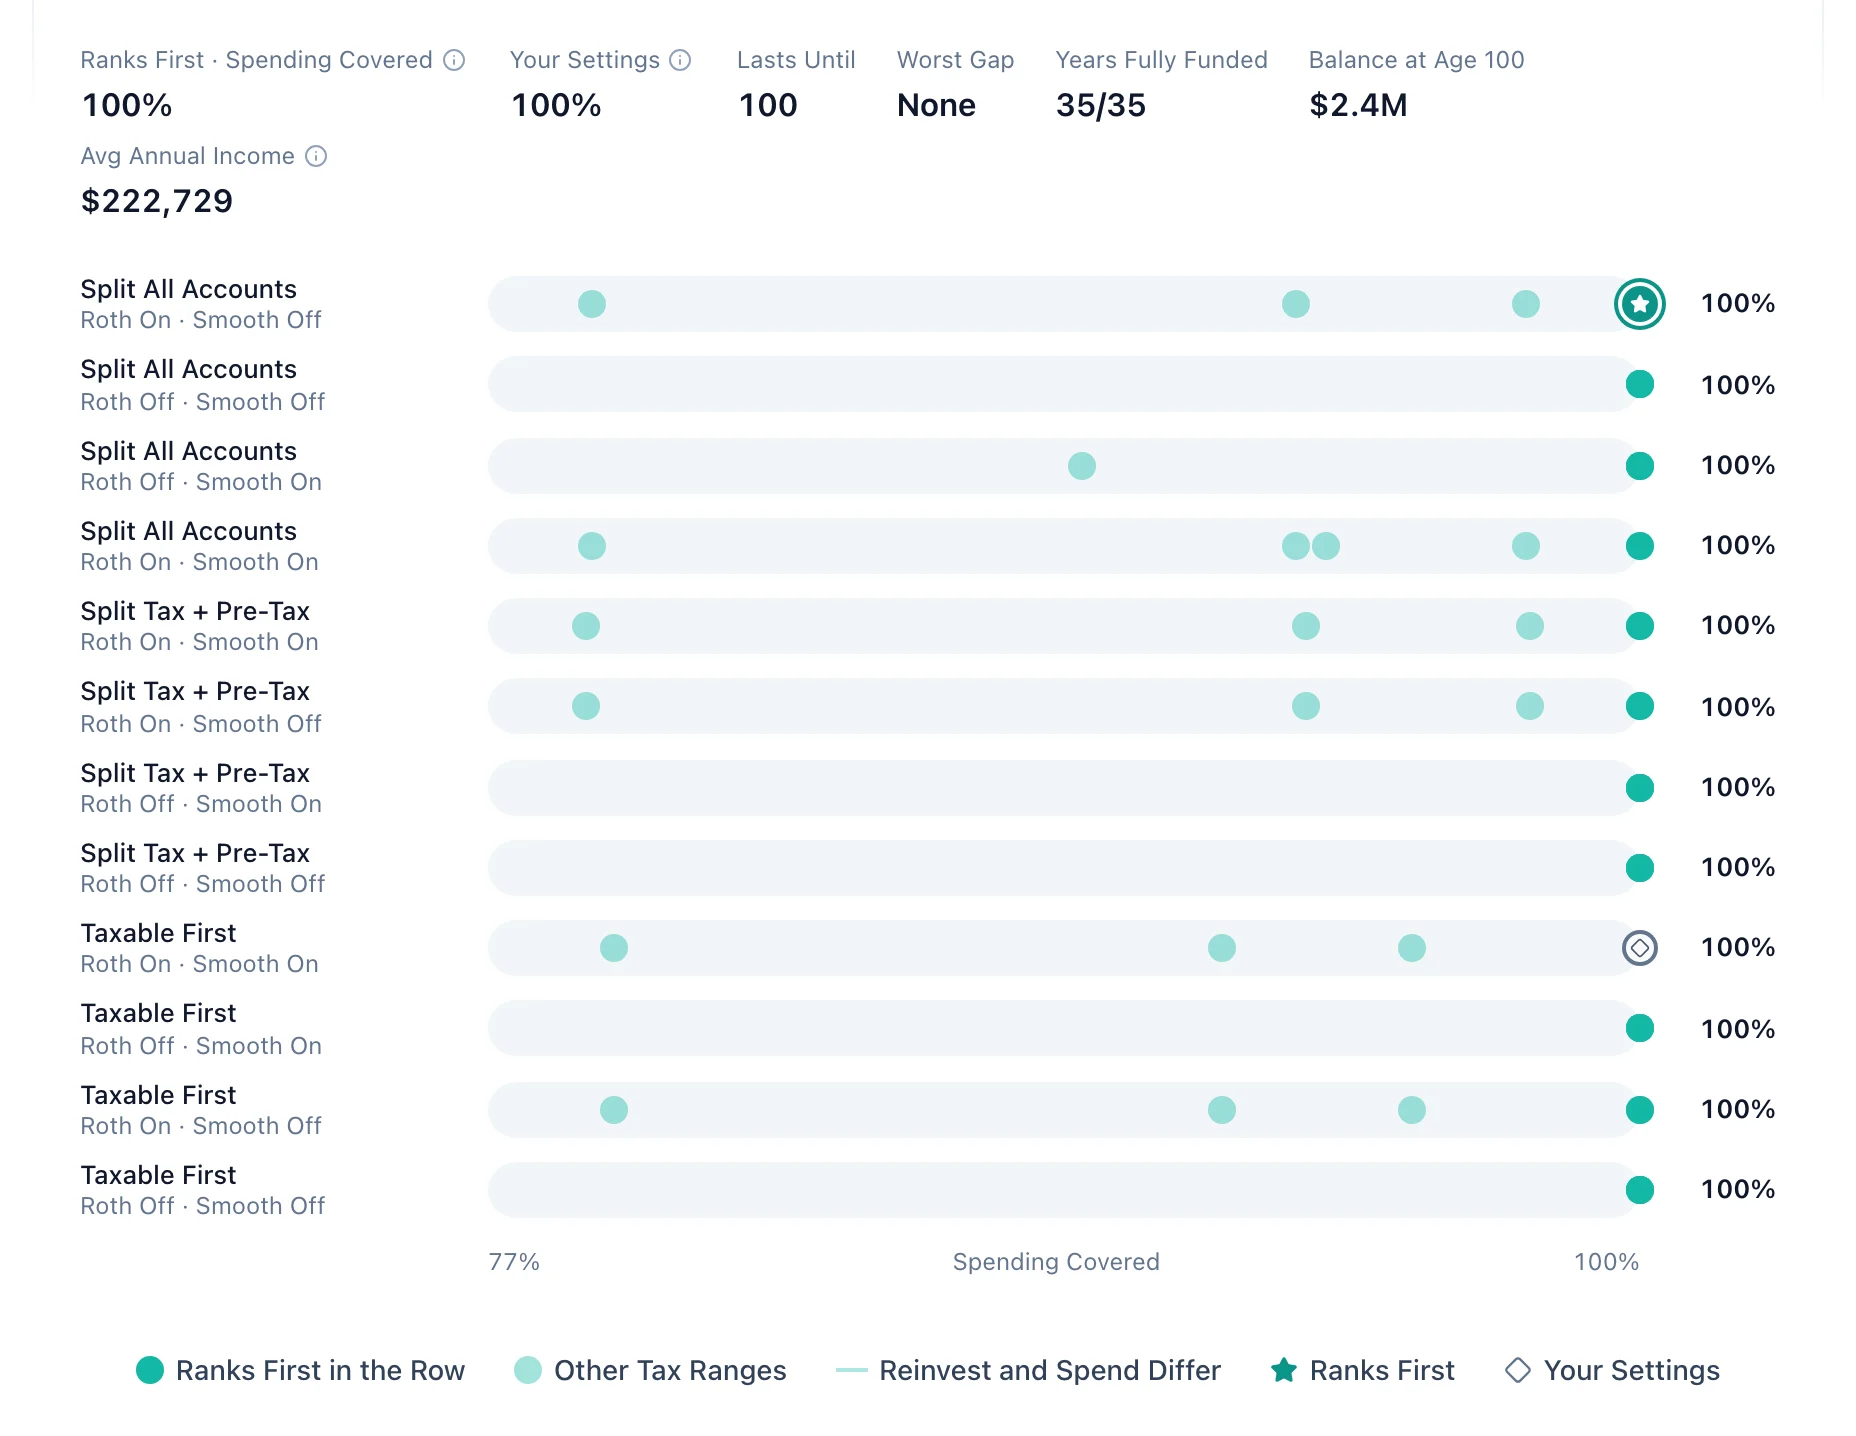
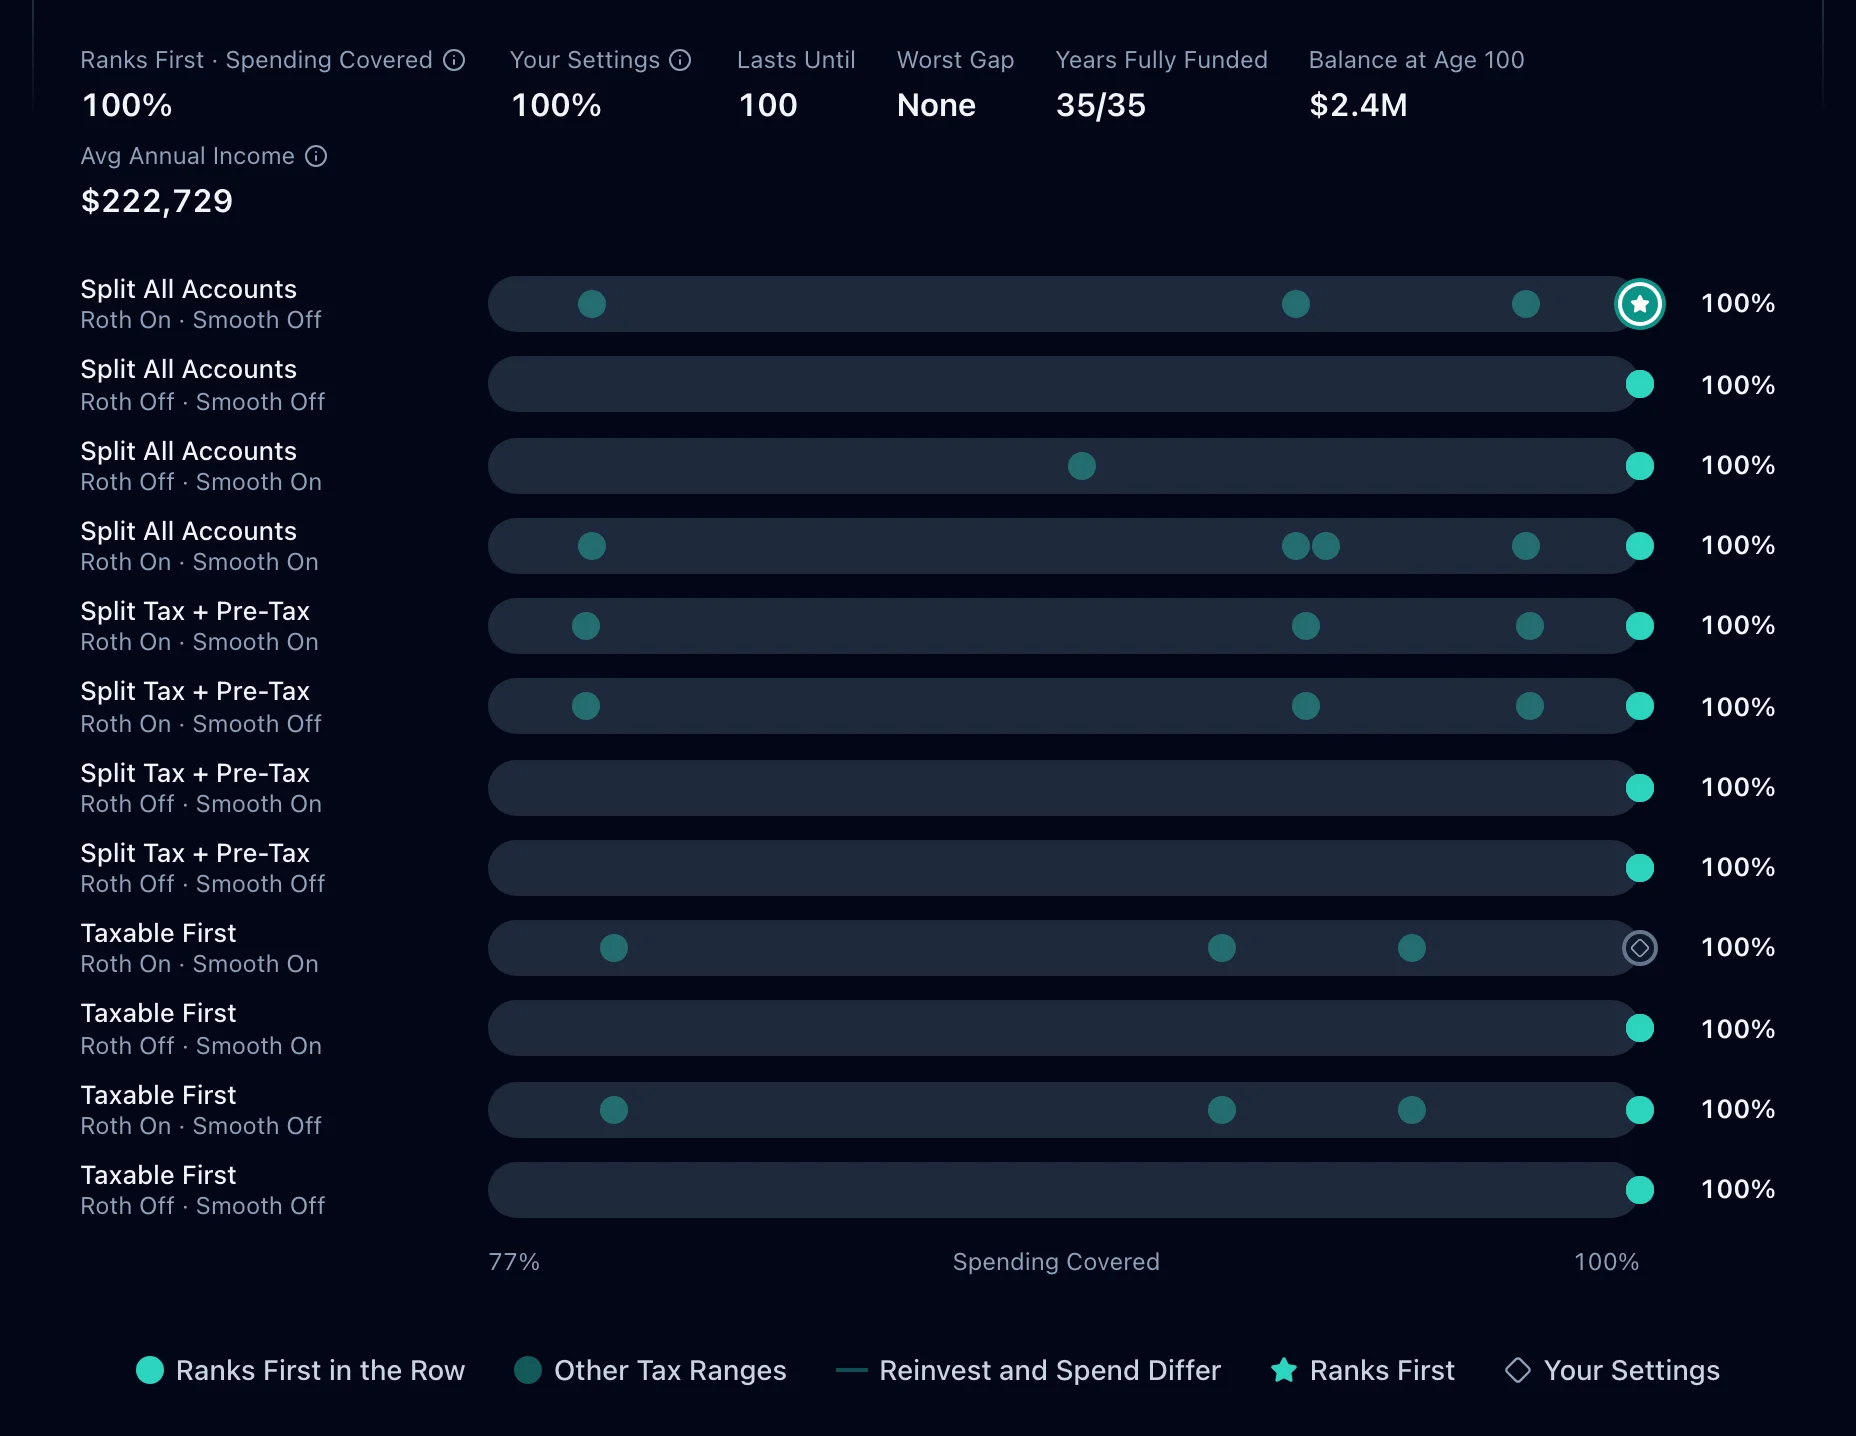
Which account to draw from first, whether to convert to Roth, and which tax bracket to stay in. invio runs these combinations through your plan and ranks them by what matters to you, such as how long your money lasts.
invio is private by design. We never ask for bank or broker logins, and we don't sell your data.
Yes, that means some manual work.
In return, nothing breaks when a bank changes its website, and you keep one record of your money that you control, for decades.
Export everything, anytime, as spreadsheets and one complete file. Delete your account whenever you want.
invio does the math on your numbers and shows where your choices lead. Every decision is yours.
Tax rules, return assumptions and allocation mixes, offered as is. Check them and change any you like.
Once a year, invio's founder publishes his own portfolio and returns, and explains what he holds and why.
See the PortfolioA flat price, never a percentage of your savings. Subscriptions pay for invio, so it has no ads.
$0
$9/month
$79/year
$6.58/month — save $29/year
You enter your accounts, debts, and goals once. invio works out an order for each month's savings, when you can reach financial independence, how your plan would have done in past markets, and how each way of drawing your money down in retirement plays out.
invio isn't an advisor and knows only what you enter. It runs the numbers on your accounts, your goals, and the settings you choose, and shows what each option leads to. Presets such as tax rules, return assumptions, and allocation mixes give you a starting point; they're offered as they are, so check them and change what doesn't fit. invio earns only from subscriptions: no commissions, no fund fees, no paid placements.
People in the U.S. who invest on their own through a 401(k), IRA, HSA, or taxable account and want a long-term plan. invio offers preset tax and account rules that follow U.S. law: starting points to check and change, with no guarantee they fit you.
Budgeting apps track what you spend. invio starts from your accounts and answers the bigger questions: where the next dollar goes, when you can stop working, and how to withdraw in retirement. You can test each plan against market history since 1928.
Bank connections run through outside companies that hold access to your accounts and break when a bank changes its website. invio skips them. You update balances yourself.
Setup means entering your accounts, debts, and goals once. After that, you update balances when you want, for example once a quarter.
Yes. The free plan includes your net worth, savings order, forecast, and four history snapshots. Pro adds the rest.